Roof insurance questions in Prairie Grove, AR
Understand the roofing scope, then separate it from the policy decision. Deductibles, depreciation and settlement terms affect what a claim pays.
Separate the roof work from the claim payment
A damaged roof creates two connected questions: what work makes the roof sound, and what the insurance policy will pay. They are answered by different evidence. The roofer assesses the physical work; the insurer applies the policy to the reported loss.
This guide uses Arkansas Insurance Department consumer material and national regulator explanations to make the terms easier to follow. It does not predict a claim outcome. Bring the roof concern to an inspection and direct coverage and deadline questions to the insurer or agent who can review the actual policy.
What roof insurance covers
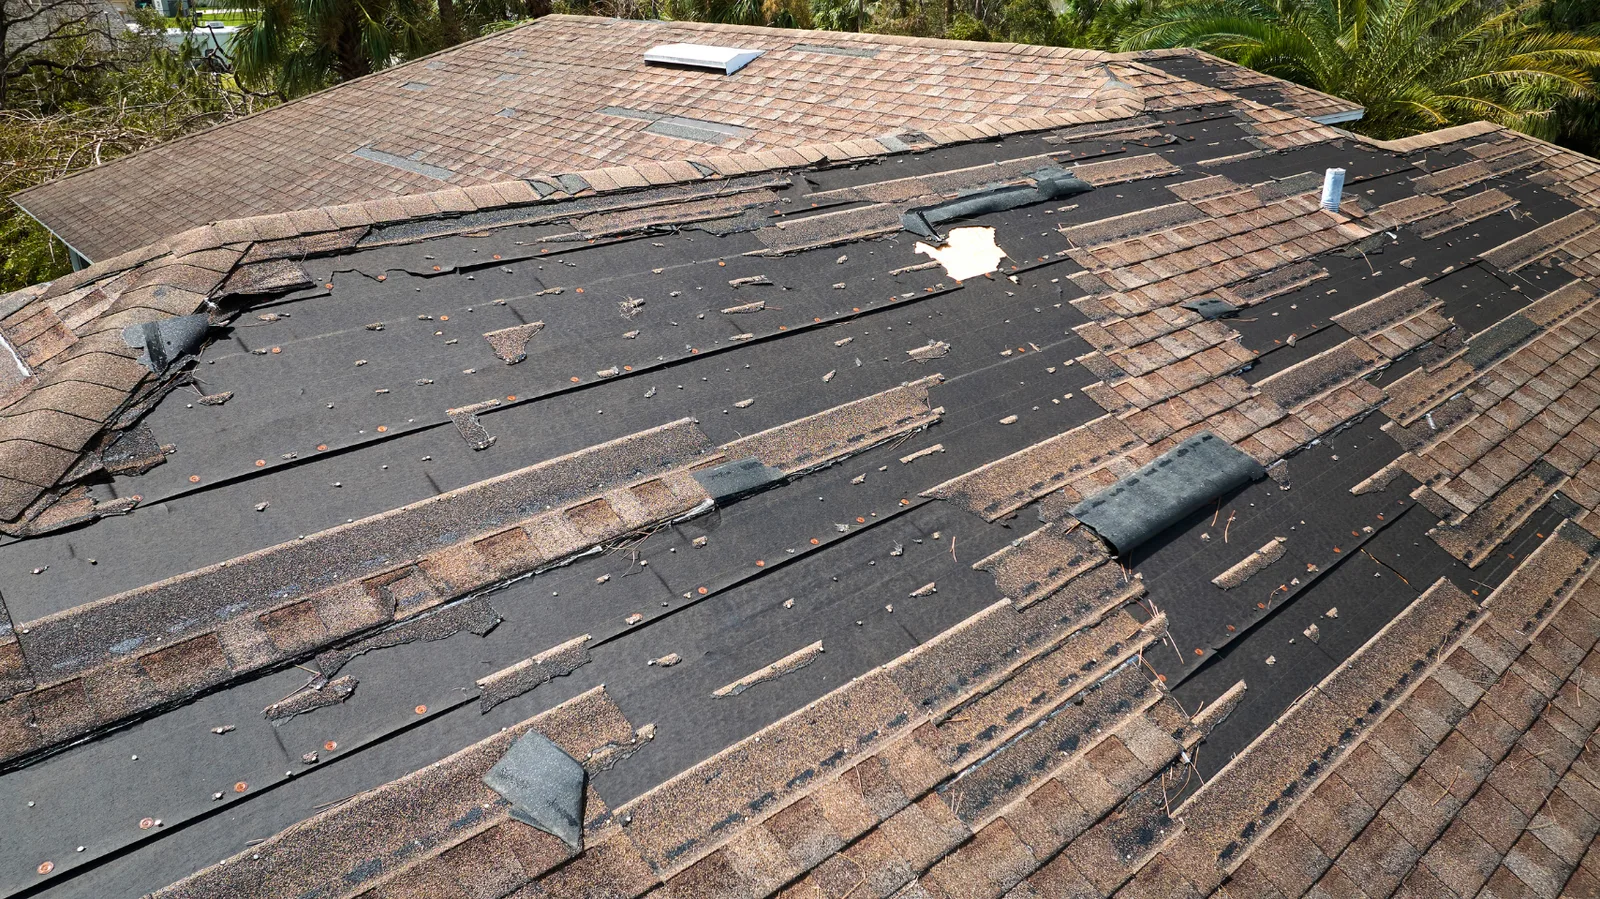
A policy may cover damage from a covered event, subject to its terms. A roof simply reaching the end of its useful service is a different issue from a sudden insured loss. Neither the roof’s age nor a storm headline decides the whole claim.
- Damage and cause
Missing material, broken shingles and failed details need assessment at the property. The repair scope should reflect those findings. A stain or nearby hail report alone does not establish the complete cause or extent.
- The deductible
The Arkansas Insurance Department’s post-storm guidance notes the importance of comparing damage with the deductible. The deductible is part of the owner’s responsibility under the policy, not an amount a roof estimate can make disappear.
- Policy-specific limits
Roof settlement endorsements, exclusions, limits and the cause of loss can change coverage. Ask the carrier to explain the provision behind its decision. The roof work may still be necessary even when some of its cost is outside the policy.
Replacement cost and actual cash value
The National Association of Insurance Commissioners distinguishes replacement cost from actual cash value. These terms describe settlement, not the house’s sale price.
From damage concern to roofing scope
The roof assessment and claim process can proceed together while keeping responsibility clear.
Protect and assess
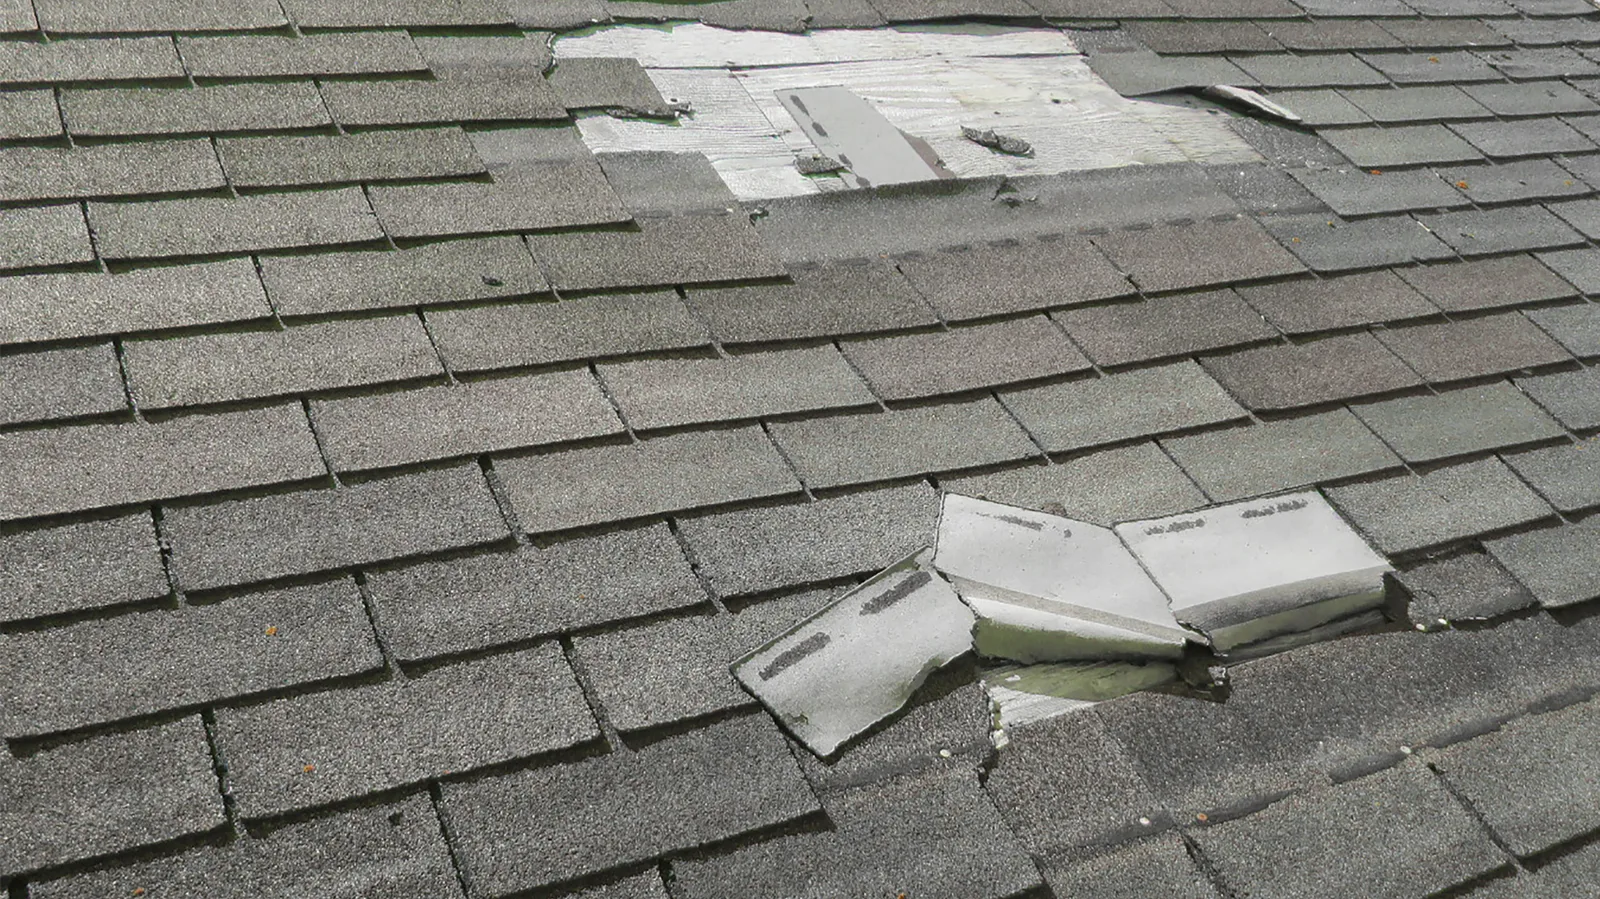
Keep clear of unsafe areas. Arrange roof assessment and suitable temporary protection when conditions allow. Arkansas regulator guidance supports reasonable steps to prevent further damage and retaining photographs and receipts.
Report to the insurer
Contact the insurer or agent promptly and ask about required information, inspection and applicable deadlines. Coordinate permanent repair with the insurer’s opportunity to inspect. Do not rely on a generic online deadline.
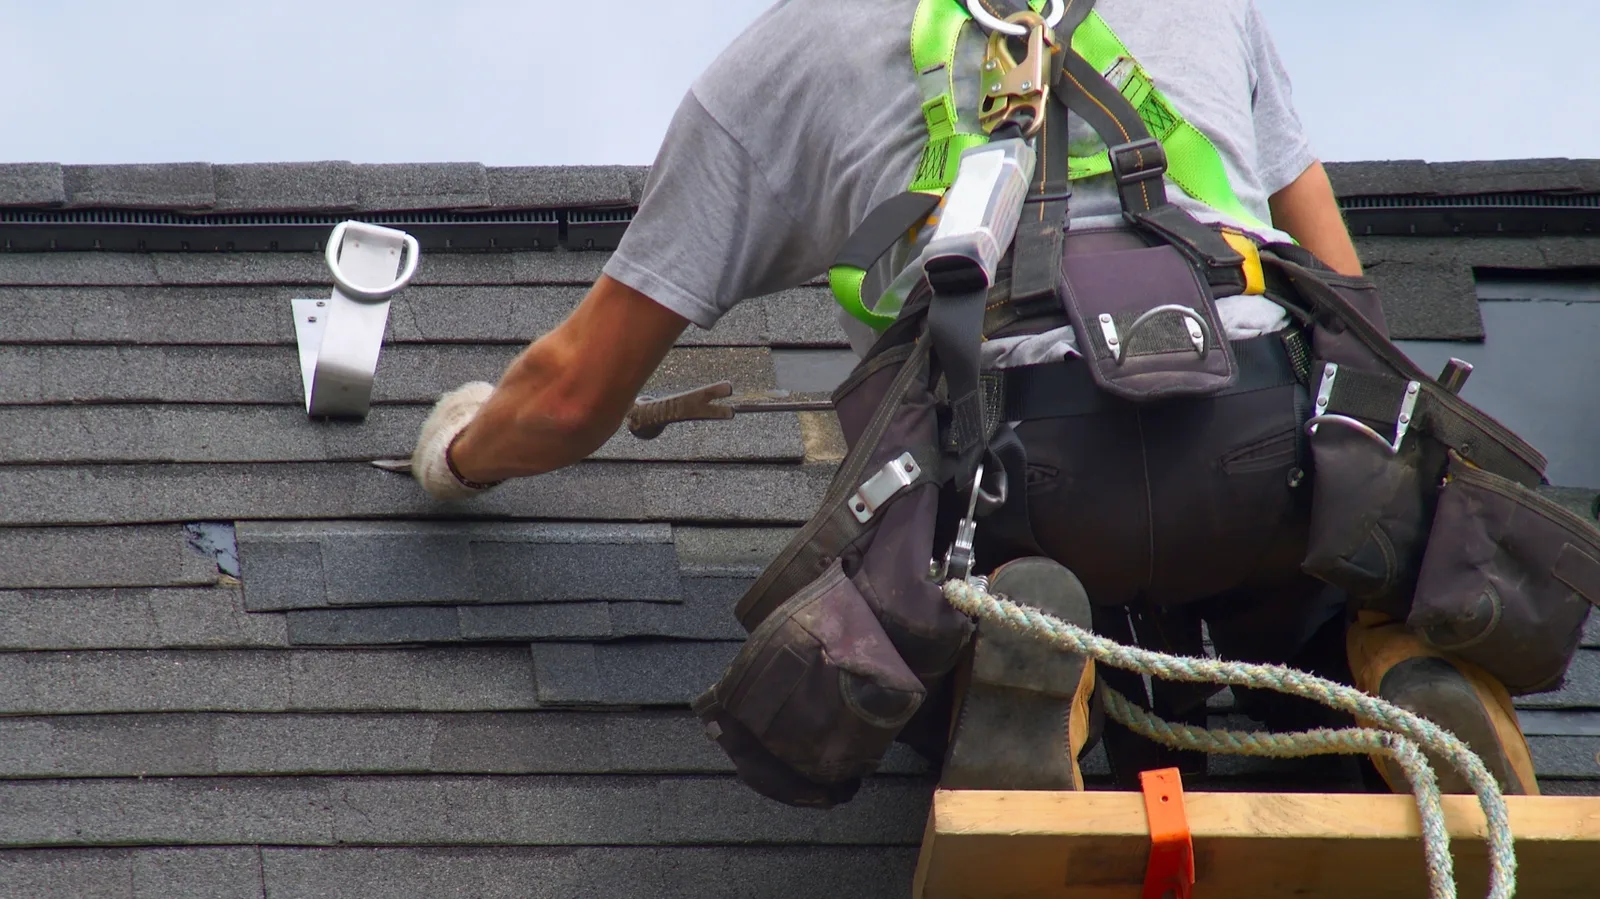
Agree the roofing scope
Compare the described repair work with the insurer’s estimate. A difference or newly exposed damage needs clarification before assuming payment. The contractor performs the agreed roof work; the insurer decides coverage.
Prairie Grove roof insurance FAQs
Will insurance replace a roof simply because it is old?
Age alone is not a covered loss. An older roof can also suffer event damage, but the cause, condition and policy terms need to be considered separately. A replacement need does not itself establish insurance coverage.
Can a roof have claim-relevant damage without an indoor leak?
Yes. Exterior damage can exist before water reaches a finished room. The roof assessment establishes the physical findings; the insurer determines whether those findings fall within the policy.
Why might the claim payment be less than the roofing price?
The deductible, depreciation, coverage limits, exclusions or differences in the accepted work can leave a gap. Ask the insurer to explain its calculation and compare it with the defined roofing scope before treating a payment as the whole budget.
Can a roofer promise that an insurer will approve replacement?
No. A roofer can explain roof condition and the proposed work, but cannot decide policy coverage or guarantee claim approval. Arkansas Consumer Services is a separate resource for unresolved insurance questions or complaints.
Begin with the condition of the roof.
Tell us what changed and whether water is entering. A free roof inspection can help define the roofing work while the insurer handles policy coverage.